Most financial plans look comfortable when life goes broadly as expected.
Income arrives on time. EMIs get paid. Investments continue. Insurance stays in place. Financial goals keep moving forward.
But that is not when a financial plan is truly tested.
A better question is:
What happens if the next twelve months are unusually difficult?
Imagine that your income stops for a few months. During the same period, a large family or medical expense comes up. Equity markets are also weak when you need money.
None of these situations is unusual by itself.
The challenge begins when two or three happen together.
That is where a financial stress test can be useful.
What is a financial stress test?
A financial stress test checks whether your financial plan can continue to work when life becomes more difficult for a while.
It is not about predicting a crisis.
Nor is it about preparing for every possible problem.
The purpose is simpler: to see whether a difficult period could force you to make decisions that may hurt your long-term financial plans.
For example, would you have to sell long-term investments? Would an unexpected expense need to be paid through a loan? Could your EMIs become difficult to manage? Would an important financial goal have to stop?
These questions tell you something that investment returns alone cannot.
They show how much financial room your plan gives you when circumstances change.
Difficult years are often about timing
A financial problem does not always begin with one major event.
Sometimes, the problem is simply bad timing.
Consider a family with regular income, a home loan, children’s education goals, SIPs and a diversified investment portfolio.
On paper, the plan may look well organised.
Now assume the main income stops temporarily.
If markets are doing well, the family may be able to sell some investments without much concern.
But what if markets are already down?
Add a large medical or family expense during the same period, and the pressure becomes much greater.
The investments may not be the problem at all.
The real problem is that money is required at the wrong time.
A sound financial plan should therefore do more than help your money grow. It should also reduce the chance that a short-term problem forces you to make a poor long-term decision.
Start with money you can access quickly
Emergency money is often judged by the return it earns.
That is not always the right way to look at it.
An emergency reserve has a different job from an equity investment.
Its main purpose is to give you time.
If income stops, accessible money can help you meet household expenses and EMIs. If a large expense comes up, that money may help you avoid selling long-term investments at an unsuitable time.
Think of it this way:
Some money is there to grow. Some money is there to give the rest of your money time to grow.
That is why readily available cash can be an important part of a financial stress test.
Check how much room your EMIs leave
Most people judge loan affordability when income is normal.
A stress test asks a different question:
What happens if income falls for a few months?
Home-loan EMIs, school fees, insurance premiums and household expenses do not stop simply because income has become uncomfortable.
That is why affordability should not be judged only by whether you can pay the EMI today.
Ask instead:
After paying my fixed expenses, how much room is still available?
A household with some spare room can adjust more easily.
A household where almost all income is already committed has fewer choices when something unexpected happens.
Check whether insurance is doing its job
Investments and insurance solve different problems.
Investments usually build money gradually for future goals.
Insurance is meant to protect your finances from certain large risks that can arrive suddenly.
A retirement goal may take twenty years to build.
A major medical bill may need to be paid this week.
Without enough insurance, money meant for retirement, education or another goal may suddenly have to solve an immediate problem.
Therefore, ask:
Which risks could seriously affect my financial plan if I had to pay for them myself?
That question makes insurance part of the financial plan rather than a separate product decision.
Decide which goals can move
Not every financial goal needs to happen on an exact date.
Some goals have less flexibility.
Children’s higher education, for example, usually follows a fairly clear timeline.
Other goals may have more room. A home upgrade, expensive holiday or early-retirement target may be moved if circumstances require it.
That flexibility matters.
A financial plan can look very precise when every goal has a fixed amount and date.
But too much rigidity can make the plan weaker during a difficult period.
Sometimes, delaying one lower-priority goal may help protect several more important ones.
Run your own difficult-year test
You do not need complicated software to do a basic financial stress test.
Take a sheet of paper and imagine this situation:
Your income is lower for six months, a large unexpected expense appears, and equity markets are weak.
Then ask yourself:
- How would we meet monthly household expenses?
- Would we need to borrow?
- Would we have to sell long-term investments?
- Could we continue paying EMIs comfortably?
- Would insurance cover the major financial risks?
- Which goals could be delayed if necessary?
You are not predicting that all of these events will happen together.
You are checking whether your financial plan would still give you choices if they did.
A strong plan does not remove uncertainty
There is also a danger in becoming too defensive.
Keeping too much money in cash, avoiding all borrowing or trying to cover every possible risk may make a plan inefficient.
The aim is not to remove every uncertainty.
It is to create enough room to deal with difficult periods.
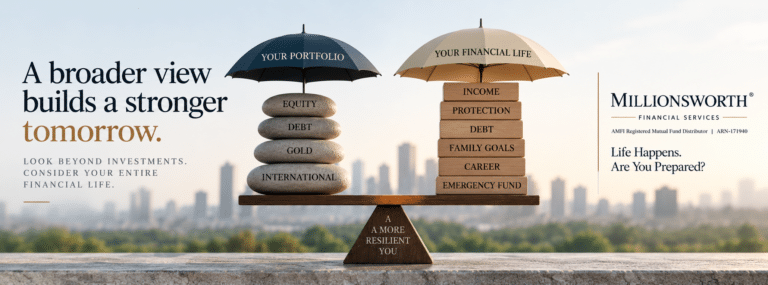
That usually means having money you can access quickly, suitable insurance, manageable debt, long-term investments that can stay invested and some flexibility in lower-priority goals.
Together, these can help one difficult year remain exactly that — one difficult year, rather than the beginning of a long-term financial setback.
One question for your next financial review
Most investment reviews begin with:
How did my portfolio perform?
That matters.
But your next financial review should also ask:
If the next twelve months are unusually difficult, has my financial plan given me enough room to manage through them without disrupting my longer-term financial journey?
That is the real purpose of a financial stress test.
A good financial plan should help you move forward when life goes as expected.
It should also help you retain choices when it does not.
Life Happens. Are You Prepared?
Millionsworth Financial Services
AMFI Registered Mutual Fund Distributor | ARN-171940
This article is for financial education and general information. Financial decisions should be considered in the context of your own circumstances, responsibilities and risk capacity.